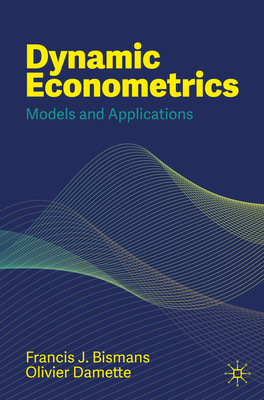
Dynamic Econometrics: Models and Applications
In stock, ships in 1-2 business days
Free standard shipping on orders over $40. ISBN 9783031729096
About this book
This textbook for advanced econometrics students introduces key concepts of dynamic non-stationary modelling. It discusses all the classic topics in time series analysis and linear models containing multiple equations, as well as covering panel data models, and non-linear models of qualitative variables. The book offers a general introduction to dynamic econometrics and covers topics including non-stationary stochastic processes, unit root tests, Monte Carlo simulations, heteroskedasticity, autocorrelation, cointegration and error correction mechanism, models specification, and vector autoregressions. Going beyond advanced dynamic analysis, the book also meticulously analyses the classical linear regression model (CLRM) and introduces students to estimation and testing methods for the more advanced auto-regressive distributed lag (ARDL) model. The book incorporates worked examples, algebraic explanations and learning exercises throughout. It will be a valuable resource for graduate and postgraduate students in econometrics and quantitative finance as well as academic researchers in this area.
Details
- Format
- Paperback
- ISBN-13
- 9783031729096
- Publisher
- Palgrave MacMillan
- Published
- February 16, 2025
- Pages
- 349
- Weight
- 18.4 oz
- Subject
- Business & Economics
Popular in Business & Economics
Browse Business & Economics
The 7 Habits of Highly Effective People: 30th Anniversary Edition
Stephen R. Covey
$16.99

Extreme Ownership: How U.S. Navy Seals Lead and Win
Jocko Willink
$24.99

Bad Blood: Secrets and Lies in a Silicon Valley Startup
John Carreyrou
$17.99
Die with Zero: Getting All You Can from Your Money and Your Life
Bill Perkins
$16.99

Crucial Conversations: Tools for Talking When Stakes Are High
Joseph Grenny
$19.99

Radical Candor: Be a Kick-Ass Boss Without Losing Your Humanity
Kim Scott
$25.99

1929: Inside the Greatest Crash in Wall Street History--And How It Shattered a Nation
Andrew Ross Sorkin
$27.99

What Could Possibly Go Right?: The Essential Journey to Scale an Enduring Culture
Danny Meyer
$25.99

I Will Teach You to Be Rich: No Guilt. No Excuses. Just a 6-Week Program That Works (Second Edition)
Ramit Sethi
$14.99
Never Split the Difference: Negotiating as If Your Life Depended on It
Chris Voss
$27.99
The Total Money Makeover Updated and Expanded: A Proven Plan for Financial Peace
Dave Ramsey
$23.99

Think Again: The Power of Knowing What You Don't Know
Adam Grant
$16.99