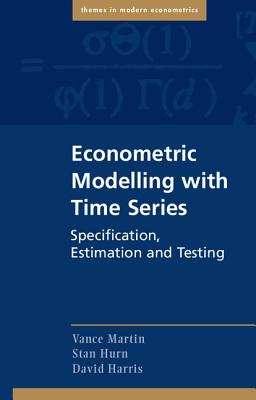
Econometric Modelling with Time Series
by Vance Martin
In stock, ships in 1-2 business days
Free standard shipping on orders over $40. ISBN 9780521139816
Formats and editions
About this book
This book provides a general framework for specifying, estimating, and testing time series econometric models. Special emphasis is given to estimation by maximum likelihood, but other methods are also discussed, including quasi-maximum likelihood estimation, generalized method of moments estimation, nonparametric estimation, and estimation by simulation. An important advantage of adopting the principle of maximum likelihood as the unifying framework for the book is that many of the estimators and test statistics proposed in econometrics can be derived within a likelihood framework, thereby providing a coherent vehicle for understanding their properties and interrelationships. In contrast to many existing econometric textbooks, which deal mainly with the theoretical properties of estimators and test statistics through a theorem-proof presentation, this book squarely addresses implementation to provide direct conduits between the theory and applied work.
Details
- Format
- Paperback
- ISBN-13
- 9780521139816
- Publisher
- Cambridge University Press
- Published
- December 28, 2012
- Pages
- 924
- Weight
- 41.6 oz
- Subject
- Business & Economics
Popular in Business & Economics
Browse Business & Economics
The 7 Habits of Highly Effective People: 30th Anniversary Edition
Stephen R. Covey
$16.99

Bad Blood: Secrets and Lies in a Silicon Valley Startup
John Carreyrou
$17.99

Extreme Ownership: How U.S. Navy Seals Lead and Win
Jocko Willink
$24.99
Never Split the Difference: Negotiating as If Your Life Depended on It
Chris Voss
$27.99
Die with Zero: Getting All You Can from Your Money and Your Life
Bill Perkins
$16.99

Crucial Conversations: Tools for Talking When Stakes Are High
Joseph Grenny
$19.99

Radical Candor: Be a Kick-Ass Boss Without Losing Your Humanity
Kim Scott
$25.99

1929: Inside the Greatest Crash in Wall Street History--And How It Shattered a Nation
Andrew Ross Sorkin
$27.99

What Could Possibly Go Right?: The Essential Journey to Scale an Enduring Culture
Danny Meyer
$25.99

I Will Teach You to Be Rich: No Guilt. No Excuses. Just a 6-Week Program That Works (Second Edition)
Ramit Sethi
$14.99
The Total Money Makeover Updated and Expanded: A Proven Plan for Financial Peace
Dave Ramsey
$23.99

Think Again: The Power of Knowing What You Don't Know
Adam Grant
$16.99